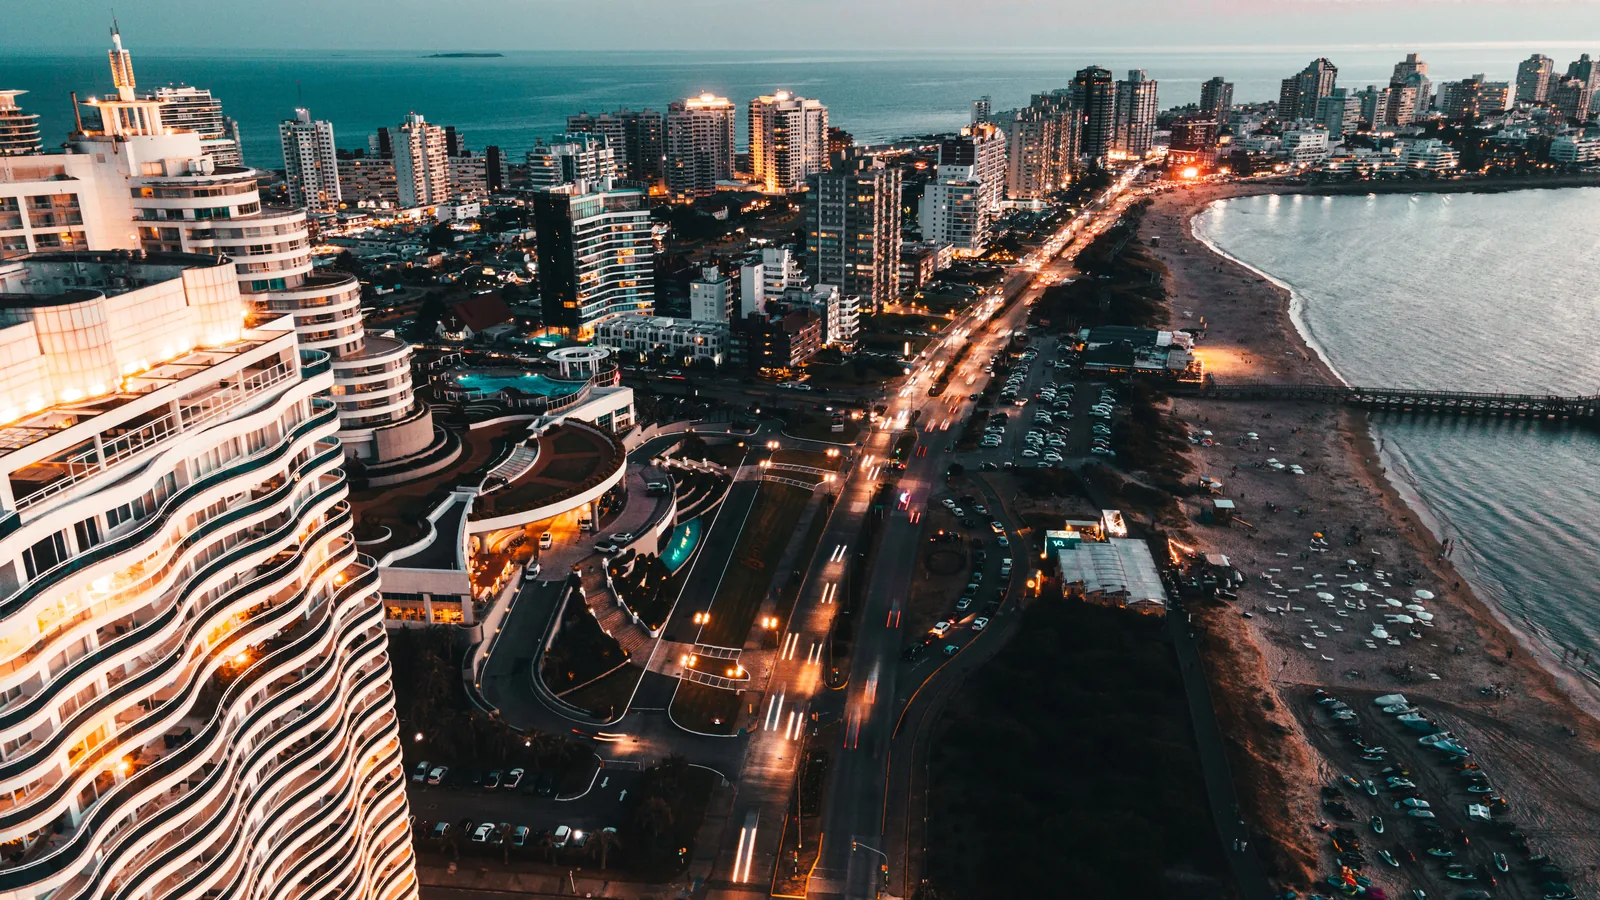
Punta del Este at dusk. Photo: Pedro Slinger / Pexels
In recent years, the search for tax residency in Latin America by high-net-worth individuals (HNWIs) has intensified. Factors such as tax burdens in countries of origin, regional political or economic instability, and the desire for a stable base for family wealth have driven many toward destinations offering a combination of low tax burden, ease of access, and a certain degree of predictability.
Paraguay emerged strongly on that map. Its pure territorial system — which essentially taxes only local-source income —, reduced tax burden, competitive cost of living, and relatively accessible residency process positioned it as a real competitor, especially among Brazilians and other profiles that prioritized immediate tax optimization. For a specific segment of investors and families, the proposition was clear and attractive.
That narrative, however, has just encountered a significant point of friction. According to an official note of Paraguay’s Supreme Court of Justice dated 5 November 2026, socializing a communication from the Superintendence of Banks, the Board of the Central Bank of Paraguay ordered the start of a resolution procedure for Ueno Bank S.A. by Resolution No. 1, Minutes No. 49, of 2 November 2026, on the ground set out in article 13(b) of Law No. 2.334/03. According to BBC News Mundo on November 5, 2026, President Santiago Peña submitted his resignation under impeachment pressure. This article does not present that resignation as a confirmed official act of the Presidency or of Congress. Regardless of the final outcome, the episode damages the perception of predictability and patrimonial security that many HNWIs were seeking. When a destination's main promise is “clear rules and stability,” a banking shock of this magnitude forces a review of the risk analysis.
In this context, Uruguay consolidates its position as the most robust and serious option in the region for those seeking to protect wealth and, at the same time, a quality base for life.
The pillars that make the difference
Institutional stability and rule of law. Uruguay is consistently classified as one of the few full democracies in Latin America, with low levels of perceived corruption and continuity of public policies across different governments. Rules do not change abruptly according to the political cycle. For an HNWI planning 10 or 20 years ahead, that institutional predictability has a value that is hard to quantify on a tax spreadsheet.
Solid and deeply dollarized financial system. The Uruguayan banking system has demonstrated historical resilience against regional crises. It is highly dollarized, operates with international compliance standards and tax-information exchange arrangements, including an agreement with the United States that official MEF and DGI pages classify as an Agreement on Exchange of Information in Tax Matters (AII) — signed 24 October 2023, in force from 10 November 2024, approved by Law 20.351. It is not presented here as a FATCA IGA. Holding savings in dollars does not eliminate banking risks.
Network of treaties and international legal certainty. Uruguay has double taxation treaties with several relevant countries, including Brazil (MEF lists the Brazil CDI as in force from 21 July 2023, with effects from 1 January 2024). This reduces the risk of challenges from the tax authority of the country of origin and facilitates cleaner structures for those who maintain economic or corporate ties abroad. The existence of treaties is not a minor detail when analyzing the robustness of a tax residency strategy.
Predictable tax framework and the impatriate regime. Uruguay maintains a predominantly territorial approach, with a specific regime for new tax residents. Under article 24-bis of Title 7 of the 2023 Compiled Text (added by article 648 of Law 20.446 of 16 December 2025; IMPO publication 8 January 2026), individuals who acquire tax residency from 1 January 2026 may opt, once, to be taxed under the Non-Residents Income Tax (IRNR) on the foreign-source capital income referred to in article 6, first paragraph, numeral 2 — for the fiscal year in which the change of residence occurs and the following ten fiscal years — provided they were not tax residents during the two immediately preceding fiscal years and did not apply the previous article’s regime (subject to the exceptions stated in the law). The option also requires, in each relevant year, either more than 183 days of physical presence in Uruguay (Title 7, article 2(A)), or real-estate investments above UI 12,500,000 (properties acquired from 1 September 2025; the fiscal cost of inland urban properties in departments without Río de la Plata or Atlantic coasts is increased by 100%), or annual capitalization of at least UI 625,000 in investment funds that finance productive projects or applied research or innovation, as regulated. After that period, those incomes fall under IRPF; article 37(B) of Title 7 sets a 12% rate for “Restantes Rentas,” with further optional regimes in article 24-bis (including a 50% IRPF rate for five additional years, or fixed UI amounts, subject to conditions). The system is more demanding than a few years ago, but it is set out in law and regulation and operates within a stable institutional framework.
Quality of life and environment for families. Beyond the fiscal aspect, Uruguay offers levels of personal security, high-standard private education, healthcare infrastructure, and a lifestyle that is especially attractive for families with children. Areas such as Carrasco, Punta del Este, José Ignacio, or La Tahona combine tranquility, nature, and first-level services. For many HNWIs, “wealth protection” is not limited to tax optimization: it includes the possibility of living peacefully and projecting a stable environment for the next generation.
Real estate as an anchor
In this framework, luxury real estate in Uruguay functions as a dual anchor: it can serve as a basis for tax residency (and, meeting thresholds, as a condition of the impatriate regime) and, at the same time, as a tangible asset that can support a long-term residential plan. A property on the coast or in a gated community can provide a base for living in Uruguay. Its value and liquidity can change; neither capital preservation nor returns are guaranteed.
Uruguay is not — nor does it claim to be — the destination with the lowest permanent tax burden in the region. Paraguay, and others, may continue to be more attractive for profiles that truly relocate, have almost exclusively foreign-source income, and tolerate greater institutional risk in exchange for a territorial system that, as a rule, does not tax foreign-source income. However, for the segment of HNWIs that prioritizes patrimonial security, institutional solidity, family quality of life, and long-term predictability, the recent crisis in Paraguay reinforces the central argument: the lowest rate is not always the most rational option.
In a regional environment where institutional shocks appear with some frequency, Uruguay stands out for something more valuable than a nominal rate: a system that, over time, has proven difficult to question. For those seeking a serious place to anchor wealth and family, that reputation remains its main competitive asset.